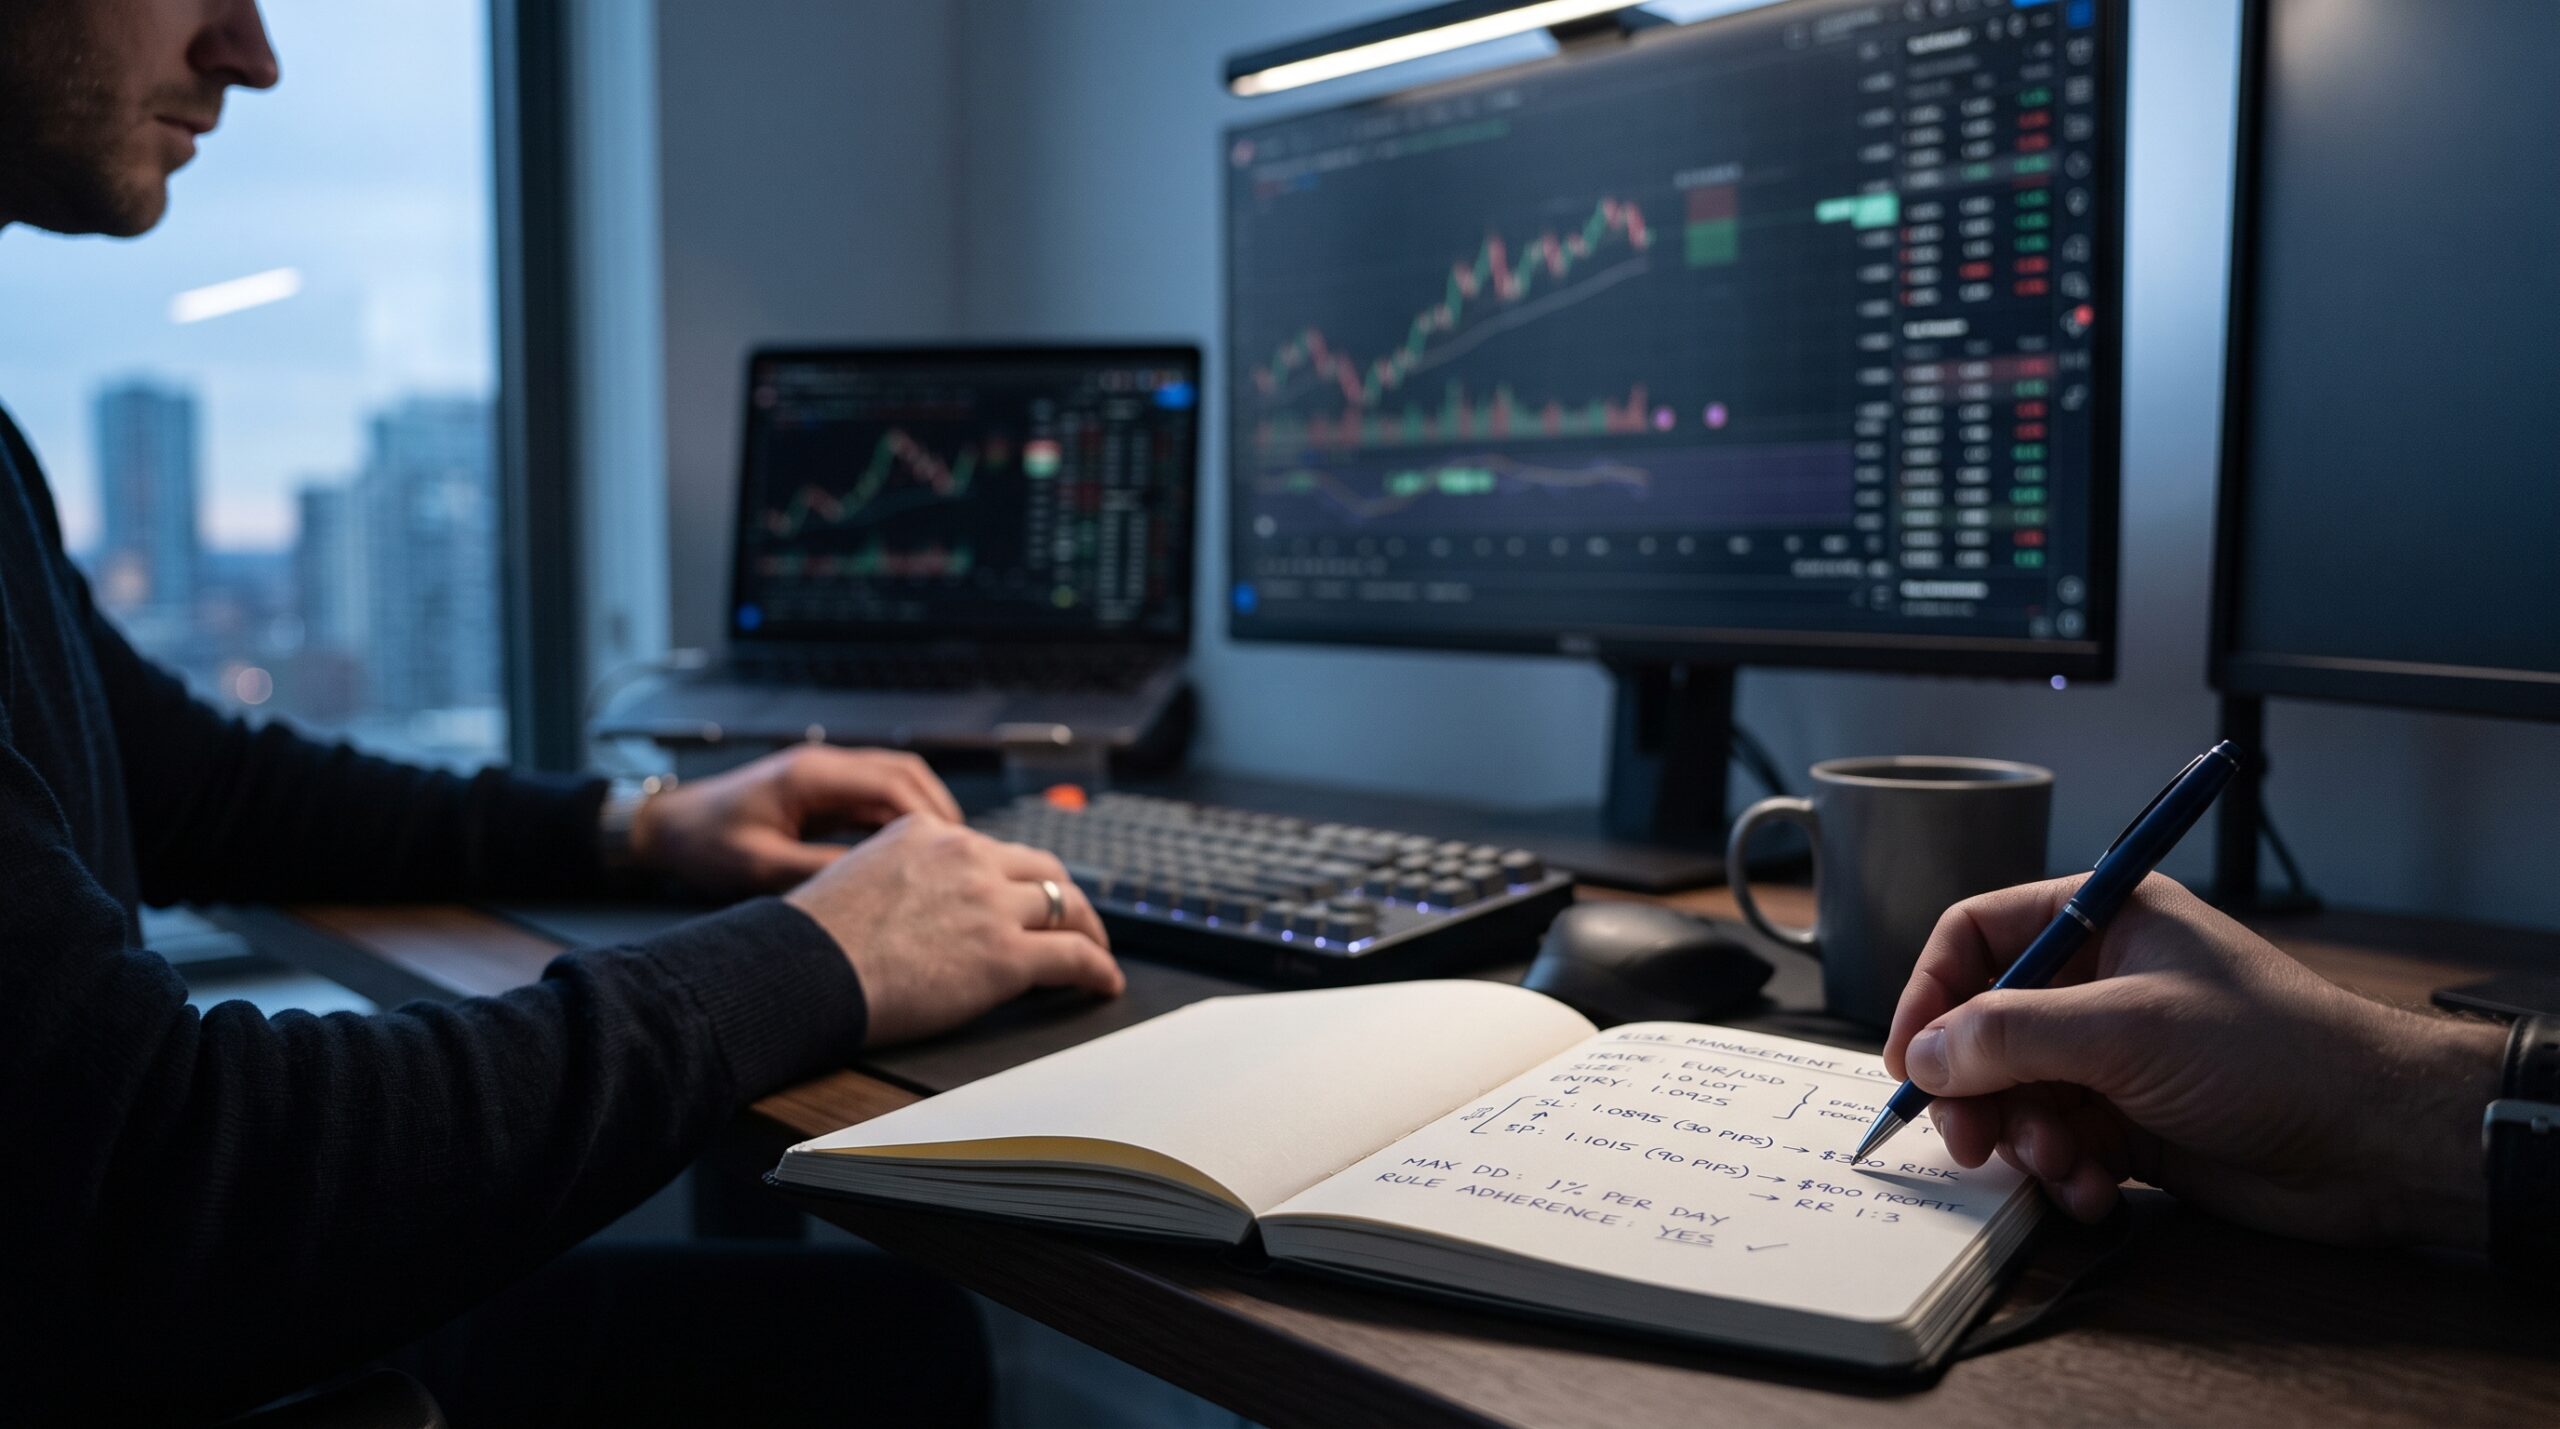
You enter a long because the chart “looks ready.” The stop sits wherever your gut flinches. The target is a round number you saw in a group chat. When the trade fails, the loss is larger than the win you hoped for—and a few of those sequences erase a month of careful work.
Risk-to-reward ratios and stop-loss placement are how professional traders keep mathematics on their side even when win rates stay imperfect. In crypto markets, where wicks are violent and liquidity is uneven, a stop is not an insult to conviction. It is a predefined invalidation point. This guide explains practical R-multiples and stop design. It is educational only—not financial advice. Trading can result in substantial or total loss.
Risk-to-Reward Without the Mystique
Risk-to-reward (R:R) compares how much you stand to lose if stopped out versus how much you stand to gain if the target hits. Risking $100 to make $200 is 1:2. Risking $100 to make $100 is 1:1. Professionals think in R units so results stay comparable across trades of different sizes.
A positive expectancy system can win less than half the time if average wins exceed average losses by enough margin after fees and funding. Chasing ultra-high R:R with tiny win probability is not automatically smart. The ratio must fit the setup’s real path in the market—not a fantasy extension drawn for screenshots.
Expert Insight From Desk Discipline
Amateurs ask, “Where will it go?” Professionals ask, “Where am I wrong—and is the payoff worth that risk?” Invalidation first, target second.
Place Stops at Invalidation, Not at Pain
A stop-loss should sit where the trade thesis fails. If you bought a breakout above resistance, a decisive return below that level may invalidate the idea. If you faded an extended move at a well-defined supply zone, acceptance through that zone may end the short. Arbitrary percentage stops—always 3%—ignore structure and often get hunted in crypto’s noisy ranges.
Use market structure, volatility, and liquidity. ATR-based buffers can reduce noise stop-outs on high-volatility pairs. Stops placed in obvious liquidity pools just beyond equal highs or lows get taken more often; sometimes you accept that and reduce size, sometimes you reframe the entry so invalidation sits in a less crowded location.
Hypothetical Breakout Long
You long a clean break and hold above a retested level. The stop belongs where the breakout is clearly rejected—not five ticks below entry because that feels comfortable. If that distance is wide, you cut position size so the dollar risk stays within your limit.
Position Size Links the Stop to Account Risk
Professionals fix risk per trade as a small percentage of equity, then back into size from the stop distance. Wider stop means smaller size. Tighter stop means larger size—but only if the tight stop is structurally honest. Size that ignores stop distance is how people “risk 1%” on paper and lose 8% on a gap or liquidation cascade.
In crypto spot markets, gaps are less common than in traditional sessions, yet thin books and exchange outages still produce slippage. On perpetual futures, leverage multiplies both the R math and the chance of forced liquidation before your stop logic matters. If you use derivatives, understand liquidation price versus stop price—and the difference can liquidate you first.
Compact Risk Math Checklist
Max account risk per trade defined. Invalidation level chosen from thesis. Distance from entry to stop measured. Position size computed from dollar risk. Fees and expected slippage included. Target requires acceptable R:R after costs. No size increase to “make the trade worth it.”
Targets, Partial Profits, and Moving Stops
R:R at entry is a plan, not a promise. Professionals scale out at predefined levels, trail stops behind structure after confirmation, or exit when the reason for the trade disappears—even if the target has not tagged. Moving a stop further away because you “need room” converts a planned risk into an open-ended one.
Be careful with breakeven stops that are too tight too early; noise can scratch a winner into a loser. Trail only when structure justifies it. Journal whether your management improved average R or merely added noise.
Expert Insight on Win Rate Obsession
A 70% win rate with 1:0.4 average R:R can lose money. A 40% win rate with 1:2 average R after costs can work. Track distribution of outcomes, not only win percentage.
Crypto-Specific Stop Realities
24/7 trading means your stop can execute while you sleep. Exchange choice, API reliability, and stop-market versus stop-limit behavior matter. Stop-limit orders may not fill in fast markets; stop-market orders may fill with slippage. Neither is universally “correct.” Match order type to liquidity and urgency.
Funding rates, weekend liquidity voids, and news prints can spike ranges. Some traders reduce size into known event risk rather than widening stops arbitrarily. Others stand aside. Protecting the account is a valid professional decision.
Hypothetical Weekend Wick
A thin Sunday book spikes through your stop and snaps back. The fill is worse than the chart’s elegant line. Your process should already assume imperfect fills on volatile pairs—especially on smaller altcoins.
Building a Repeatable Stop Protocol
Write rules: invalidation definition per setup type; maximum R risk; minimum planned R:R after fees; when partials are allowed; when to cancel a trade before entry if the stop must sit too far for your size. Review stopped trades monthly. Were stops too tight for volatility? Were theses vague so every level felt arbitrary?
Professionals do not eliminate losing trades. They eliminate undefined losses. That is the entire game.
FAQ
What is a good risk-to-reward ratio?
Many discretionary traders aim for setups that offer at least about 1:1.5 or 1:2 after costs, but only when the market structure supports it. There is no universal magic number.
Should I always use a stop-loss?
Defined risk is a core professional habit. How you implement it (hard stop, mental stop with discipline, options hedge) depends on style and platform—but unlimited downside is not a plan.
Why do my stops keep getting hit?
Possible causes include stops inside noise, obvious liquidity placement, oversized positions forcing tight stops, or setups with poor edge.
Is a percentage stop better than a structure stop?
Structure- and volatility-aware stops usually align better with thesis invalidation than fixed percentages alone.
Do professional traders move stops?
They may trail or protect profits by rule. Moving stops farther to avoid admitting a loss is rarely part of a robust process.
Is this trading advice?
No. It is education. Crypto trading involves high risk of loss, including total loss of capital.
Define the Loss Before You Chase the Win
Risk-to-reward ratios and stop-losses are how professional traders translate chart ideas into bounded experiments in crypto markets. Invalidation sets the stop; account risk sets the size; realistic targets set whether the trade is worth taking. Everything else is commentary.
Pick your last five trades and recalculate planned R:R at entry using structure-based stops. If the stops were vibes and the targets were wishes, rewrite your checklist before the next order. The market will keep offering excitement. Your stops decide whether that excitement is allowed to compound—or allowed to harm you.